
Table of Contents
Buy Now, Panic Later : The Psychology of “Doom Spending”
Open any Gen Z-heavy corner of the internet and you’ll find the same joke on a loop: “the economy is terrible, so I bought a $60 candle.” It reads as self-aware, even a little funny — but underneath the joke is a real and remarkably consistent behavioral pattern that researchers and financial experts have started calling “doom spending.” Multiple recent surveys put the share of Gen Z who admit to it somewhere between roughly a third and over 40 percent, making it one of the most talked-about financial behaviors of this generation.
What makes doom spending genuinely interesting isn’t just that it happens — impulsive spending is nothing new — but why it happens, and why it seems to be intensifying specifically among the generation that, on paper, has the least disposable income and the most financial anxiety of any adult cohort today. This piece digs into the psychology behind the pattern: what’s driving it, why logic alone doesn’t seem to slow it down, and what actually helps.
What Doom Spending Actually Looks Like
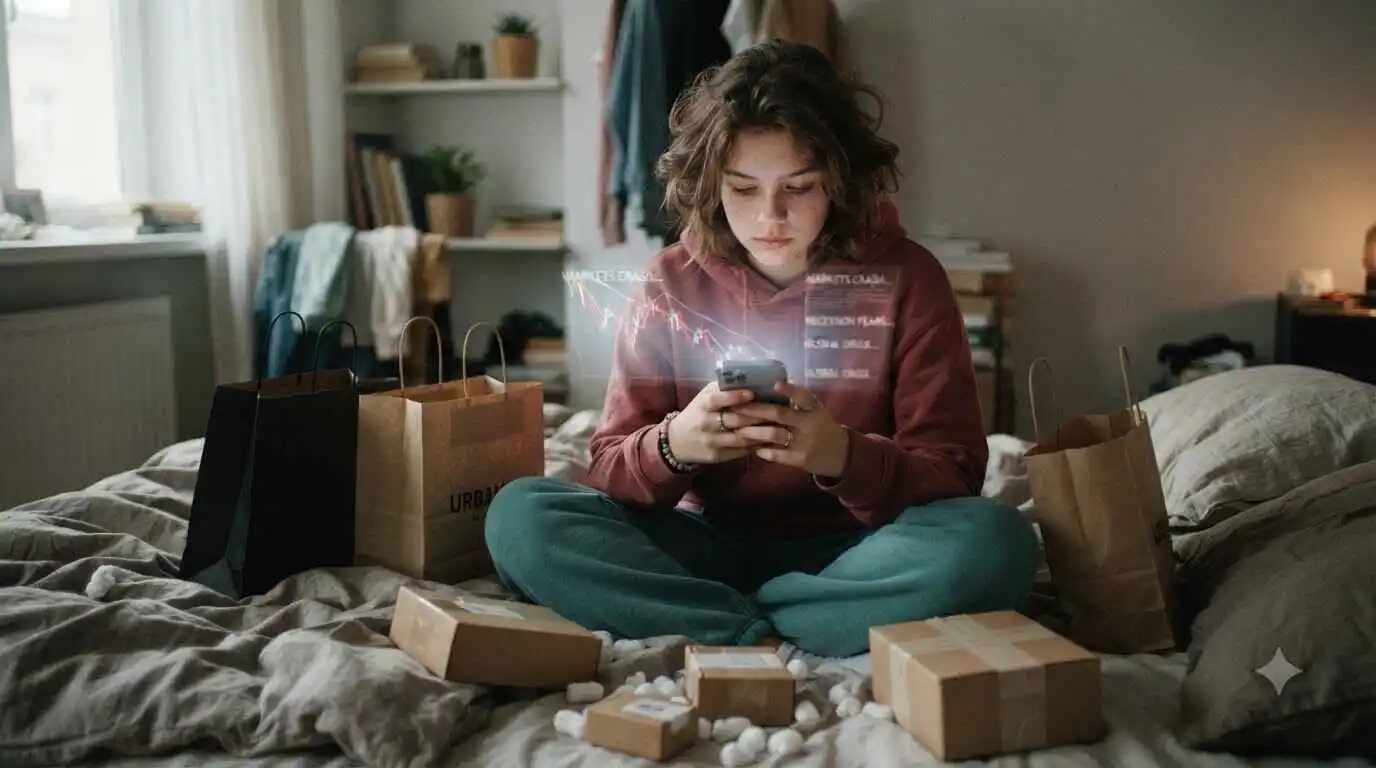
Doom spending describes impulsive, often unplanned purchases made specifically to relieve feelings of anxiety, hopelessness, or loss of control — frequently in response to news about inflation, the job market, housing costs, or broader geopolitical instability. It isn’t the same as simply enjoying shopping, or occasionally treating yourself after a hard week. The defining feature is the emotional trigger: the purchase functions less as a want and more as a pressure valve.
Financial technology company Credit Karma’s research has repeatedly found Gen Z reporting the highest rates of this behavior among generational cohorts, alongside Millennials close behind. One recent survey found that only a small share of Gen Z doom spenders said the behavior actually made them feel better afterward — most described the relief as fleeting, often followed by a familiar wave of regret.

Why This Generation, Specifically
A financial environment unlike previous generations faced
Gen Z is coming of age during a stretch marked by high housing costs relative to income, a turbulent job market for early-career workers, rising prices across daily essentials, and persistent conversation about looming economic downturns. Multiple surveys have found a majority of Gen Z living paycheck to paycheck, with the share reporting this reality climbing significantly over just the past couple of years.
A shrinking sense that delayed gratification pays off
For previous generations, the implicit financial contract was fairly straightforward: save consistently, avoid unnecessary debt, and long-term stability would generally follow. A significant portion of Gen Z reports skepticism that this contract still holds, citing concerns about housing affordability and the difficulty of building wealth compared to their parents’ generation. When the long-term payoff of restraint feels uncertain or even unlikely, the psychological pull of near-term comfort becomes relatively more powerful.
Constant exposure to bad news
Gen Z is the first generation to grow up with a smartphone as a near-constant companion, and with it, near-continuous exposure to distressing headlines through social media feeds rather than a single evening news broadcast. This creates a very different baseline of ambient stress — one that doesn’t switch off at the end of a broadcast, but persists in the background of daily scrolling.
Boredom as an underestimated driver
Anxiety isn’t the only force at play. Some recent survey data points to boredom as a distinct and significant contributor to unplanned Gen Z purchases, particularly given how much time this generation spends on shopping apps and social platforms where idle scrolling can slide easily into an impulse buy, especially when paired with influencer content or a countdown-style sale.
The Psychology Behind the Purchase
A search for control in an uncontrollable moment. When broader circumstances — inflation, job security, geopolitical instability — feel completely outside a person’s influence, a small, concrete purchase offers something rare: an immediate, tangible decision they get to make and control, even if the underlying stress remains untouched.
Emotional self-soothing. Psychologists often group doom spending with other self-soothing behaviors, like stress eating or excessive screen time, where the brain seeks quick relief from an uncomfortable emotional state through a small, accessible reward that delivers a brief dopamine lift.
The “why bother saving” mindset. If long-term financial security feels statistically unlikely regardless of individual discipline, the psychological cost-benefit calculation shifts. Spending in the present can start to feel like the more rational choice when the future payoff of saving feels abstract or improbable.
Social permission and normalization. Doom spending has become something of a cultural in-joke online, discussed openly and often humorously across social platforms. This normalization can lower the psychological barrier to the behavior, since it no longer feels like a private failure but a shared, almost communal coping ritual.
Reduced friction at checkout. Modern shopping tools — one-click purchasing, buy-now-pay-later services, and algorithmically personalized recommendations — are specifically designed to reduce the natural pause between impulse and action, making it easier than ever for an anxious moment to become a completed transaction within seconds.
What Gen Z Tends to Buy — and Why It Matters
Doom spending isn’t evenly distributed across categories. Surveys and retail data point to beauty and skincare products, clothing and accessories, food delivery, small home goods, and entertainment subscriptions as especially common categories. Financial planners who work with younger clients have also noted gendered patterns, with young women more often citing clothing and beauty purchases, and young men more frequently citing gaming-related spending.
Notably, holiday shopping data has shown particularly sharp spikes tied to stressful news cycles, with one analysis finding Gen Z holiday spending rising by a meaningful double-digit percentage year-over-year during a period marked by heightened economic and political anxiety — evidence that this isn’t a purely individual quirk, but a pattern that shifts measurably in response to collective stress.
Is Doom Spending Actually Reckless — Or Is the Narrative Too Simple?
It’s worth pushing back gently on the framing that Gen Z is simply careless with money. Some retirement-readiness research has actually found younger workers on relatively solid long-term footing compared to older generations, partly thanks to automatic enrollment features in modern retirement plans that don’t rely on individual willpower to function.
This suggests a more nuanced reality: doom spending may reflect a specific coping response to acute stress, layered on top of financial behavior that, in aggregate and over the long run, isn’t necessarily worse than previous generations’ habits at the same age. The headline narrative of a uniquely reckless generation may say more about how visible this generation’s spending is on social media than about any real generational deficiency in financial judgment.
The Real Cost of the Coping Mechanism
Even if doom spending isn’t evidence of broad recklessness, it isn’t without real cost. Repeated impulsive purchases, particularly when financed through credit or buy-now-pay-later services, can compound into meaningful debt over time, even when each individual purchase feels small and harmless in isolation. It can also quietly erode the ability to build an emergency fund, which matters enormously given how many young adults already report having little to no short-term savings buffer.
Perhaps most tellingly, most people who engage in doom spending don’t report it actually solving the problem it’s meant to address. The anxiety about the economy, the future, or the news cycle typically remains fully intact after the purchase — sometimes joined by a new layer of financial stress about the money just spent.
If spending in response to stress is starting to feel less like an occasional treat and more like a hard-to-control pattern that’s affecting your ability to pay bills or save, it can help to talk it through with a financial counselor or, if it’s tangled up with anxiety more broadly, a mental health professional. Neither conversation requires shame — just curiosity about what the spending is actually trying to soothe.
What Actually Helps
Build in a pause. A short, deliberate waiting period — even just overnight — before non-essential purchases interrupts the impulse-to-action pipeline that same-day shipping and one-click checkout are specifically designed to shorten.
Curate the feed. Reducing exposure to accounts and content that reliably trigger anxiety, whether through unfollowing, muting keywords, or scheduling specific times to check the news rather than scrolling continuously, can lower the baseline stress that fuels the urge to spend.
Separate discretionary money physically. Moving a fixed, modest amount of “fun money” into a separate account each month creates a visible, hard boundary, making it easier to notice when spending has moved beyond that intentional allowance.
Name the emotion before the purchase. Pausing to ask “what am I actually feeling right now” before checking out can be enough to interrupt the automatic loop between anxiety and spending, redirecting toward a lower-cost coping option instead.
Find lower-cost alternatives for the same emotional need. If the goal is a sense of control, a small, achievable task — tidying a space, finishing a short task list, or a quick workout — can sometimes deliver a similar psychological payoff without the financial cost.
Address the systemic layer where possible. Financial experts increasingly note that individual coping strategies alone won’t fully resolve a pattern rooted in real structural pressures like housing costs and wage stagnation, which is part of why broader conversations about affordability and financial literacy access matter alongside personal habit changes.
The Bigger Picture
Doom spending isn’t really a story about Gen Z lacking discipline. It’s a story about what happens when a generation absorbs an unusually steady diet of economic anxiety through an unusually persistent information stream, while facing genuinely higher costs and murkier long-term financial prospects than the generations that came before them. The purchase becomes a stand-in for control in moments where control feels otherwise unavailable.
Understanding the psychology behind the pattern doesn’t excuse the financial strain it can create, but it does reframe the conversation in a more useful direction — away from judgment, and toward the underlying question worth actually solving: what would it take for this generation to feel enough stability, and enough hope about the future, that a stressful headline doesn’t quietly become a cart full of items at checkout.
Frequently Asked Questions
What exactly is “doom spending”?
Doom spending is the pattern of making impulsive, often unnecessary purchases to cope with anxiety, hopelessness, or a sense that the future feels uncertain or out of one’s control, rather than to fulfill a planned need.
Is doom spending mostly a Gen Z phenomenon?
It shows up across generations, but survey data consistently shows Gen Z reporting it at the highest rates, often alongside Millennials, with roughly a third to over 40 percent of Gen Z respondents admitting to the behavior in various recent surveys.
Why is it called “doom” spending specifically?
The term pairs the everyday habit of “doomscrolling” — endlessly consuming negative news online — with impulsive spending, capturing how anxiety absorbed from constant bad news often gets soothed, temporarily, through a purchase.
Does doom spending actually make people feel better?
Rarely for long. Several surveys have found that only a small minority of self-identified doom spenders say the behavior genuinely improved their mood, with most describing the relief as brief and often followed by regret or added financial stress.
What kinds of things do people buy when doom spending?
Common categories include beauty and skincare products, clothing and accessories, food delivery, subscriptions, small home goods, and impulse buys spotted on social media, though it varies by individual and what feels like an accessible, immediate treat.
Is doom spending the same as retail therapy?
They overlap but aren’t identical. Retail therapy is a broader, older concept describing shopping to boost mood in general, while doom spending specifically ties the behavior to anxiety about large-scale uncertainty — the economy, geopolitics, climate, or the news cycle.
Why does Gen Z feel especially drawn to this behavior?
Many economists and psychologists point to a mix of factors: coming of age during major economic disruption, high living costs relative to income, skepticism about long-term financial planning paying off, and near-constant exposure to distressing news through social media.
Is social media a major driver of doom spending?
Yes, it plays a significant role in multiple ways: exposure to anxiety-inducing news, targeted advertising, influencer-driven fear of missing out, and algorithmically surfaced content that can normalize impulsive buying as a coping mechanism.
What psychological need does doom spending fulfill?
It often provides a small, immediate sense of control and agency in a moment when broader circumstances — the economy, job security, housing costs — feel completely outside one’s control, even if that sense of control is short-lived.
Is doom spending a form of self-soothing?
In many cases, yes. Psychologists often place it alongside other self-soothing behaviors like stress eating or excessive screen time, where a small, accessible action provides temporary emotional relief from a larger, harder-to-address source of stress.
Does boredom play a role, separate from anxiety?
Yes. Some research points to boredom as its own distinct driver, particularly for younger consumers who spend significant time on shopping apps and social platforms where browsing can drift easily into impulsive purchasing.
Why do people sometimes spend more during uncertain economic times, rather than less?
It can seem counterintuitive, but for some, the belief that saving “won’t make a real difference” against larger economic forces can reduce the perceived value of restraint, making present-moment comfort feel like the more rational choice in the moment.
Is this connected to a broader loss of trust in long-term financial planning?
Many surveys suggest yes — a meaningful share of Gen Z respondents report skepticism that traditional milestones like homeownership or comfortable retirement are realistically achievable for them, which can reduce the perceived payoff of delayed gratification.
Are tax refunds a common trigger for doom spending?
Survey data suggests a notable share of Gen Z who expect a refund plan to spend most or all of it, sometimes citing broader economic anxiety or recession concerns as part of their reasoning.
How does doom spending affect long-term financial health?
Repeated impulsive spending, especially when it involves credit rather than available cash, can contribute to rising debt, reduced savings, and difficulty building an emergency fund, compounding financial stress over time even though each individual purchase feels minor.
Is Gen Z actually worse at saving than older generations?
Not necessarily. Some retirement-readiness research has found younger workers benefiting from features like automatic retirement plan enrollment, suggesting that headline narratives about reckless spending don’t always reflect the fuller financial picture.
Does doom spending always involve going into debt?
No, though it often intersects with credit use, particularly with tools like buy-now-pay-later services, which can make impulsive purchases feel smaller and more manageable in the moment than they are in total.
What role does “buy now, pay later” play in this trend?
These services can lower the immediate psychological barrier to a purchase, since the visible cost feels smaller, which can make it easier to rationalize a doom-spending purchase even when it isn’t truly affordable.
Are influencers and TikTok trends part of the problem?
Many surveys point to social media content, including short-form video trends around specific products, as a meaningful influence on impulsive purchases, particularly when that content ties into broader anxieties like inflation or shortages.
Is panic buying related to doom spending?
They’re related but distinct. Panic buying is typically driven by fear of scarcity or price increases, while doom spending is more broadly about emotional relief from anxiety, though the two often show up together during periods of economic uncertainty.
Can doom spending be a symptom of a larger mental health pattern?
For some people, frequent impulsive spending tied to anxiety can be connected to broader patterns like generalized anxiety or difficulty with emotional regulation, and may be worth discussing with a mental health professional if it feels hard to control.
How can someone tell the difference between occasional treat spending and a real pattern?
A useful marker is whether the spending is a rare, planned indulgence versus a frequent, largely unplanned response to stress that leaves a person feeling regretful, anxious about money, or unable to stick to a budget afterward.
What practical strategies help reduce doom spending?
Common strategies include building in a short waiting period before non-essential purchases, unfollowing accounts that trigger anxiety-driven scrolling, using separate accounts for discretionary spending, and identifying alternative, lower-cost ways to self-soothe during stressful news cycles.
Does limiting news consumption actually help?
Many people find that reducing time spent doomscrolling — through app limits, muted keywords, or scheduled news check-ins rather than constant exposure — noticeably reduces the anxious spikes that often precede impulsive spending.
Is it realistic to expect Gen Z to simply spend less during uncertain times?
Most financial experts frame this less as a willpower issue and more as a systemic one, noting that meaningful change likely requires addressing underlying financial pressures like housing costs and wage growth, alongside individual coping strategies.
Are budgeting apps effective against doom spending?
They can help by adding a layer of visibility and friction before a purchase, particularly ones that show real-time spending totals or send alerts, though their effectiveness depends heavily on whether a person actually engages with them regularly.
Should someone feel ashamed about doom spending?
Shame tends to make the underlying anxiety worse rather than better. Most experts recommend approaching the pattern with curiosity rather than self-judgment, treating it as useful information about unmet emotional needs rather than a personal failing.
Is doom spending likely to fade as the economy stabilizes?
It’s tied closely to perceived uncertainty, so periods of greater economic and social stability tend to correlate with reduced reports of the behavior, though underlying habits and coping patterns can persist even after conditions improve.
Do brands and marketers deliberately target doom spending behavior?
Some marketing strategies do lean into urgency, scarcity, and emotional relief messaging that can resonate with anxious consumers, which is part of why building awareness of the pattern can help people recognize when they’re being nudged toward an impulsive purchase.
What’s the healthiest way to think about doom spending going forward?
Treating it as a signal rather than a flaw — a sign that stress or anxiety needs an outlet — while building small, sustainable financial habits and lower-cost coping tools tends to be more effective long-term than trying to eliminate the urge through willpower alone.
Disclaimer: The content on this blog is for informational purposes only. The author’s opinions are personal and not endorsed. Efforts are made to provide accurate information, but completeness, accuracy, or reliability are not guaranteed. The author is not liable for any loss or damage resulting from the use of this blog. It is recommended to use the information on this blog at your own discretion.
